Can a Non-Resident Apply for Probate in Hong Kong?
Key Takeaway Yes. A person who lives outside Hong Kong may be able to apply for a Hong Kong grant of representation. Residence is not the only test. The applicant…
For companies conducting cross-border business through Hong Kong, company incorporation is only one part of the tax planning and compliance process.
When a Hong Kong company receives income from another jurisdiction, it may need to prove its Hong Kong resident status before claiming benefits available under a Comprehensive Double Taxation Agreement or Arrangement (DTA).
This is where the Hong Kong Certificate of Resident Status (CoR) becomes relevant.
A Certificate of Resident Status is issued by the Hong Kong Inland Revenue Department (IRD) to eligible Hong Kong residents for the purpose of claiming benefits under an applicable DTA.
A Certificate of Resident Status is an official document used to provide evidence that an applicant is a Hong Kong resident for the purposes of a particular DTA.
For businesses operating internationally, the certificate may be relevant when dealing with cross-border income such as dividends, interest, royalties or other income for which treaty benefits are being claimed.
However, obtaining a CoR does not automatically guarantee a tax reduction or exemption overseas. The tax authority of the relevant treaty partner ultimately determines whether the conditions for the particular DTA benefit have been satisfied.
According to the IRD, eligible applicants generally include:
For a Hong Kong-incorporated company, the application process has also been simplified compared with the previous approach. Since revised CoR forms took effect in June 2023, an entity incorporated or established in Hong Kong is generally not required to provide full details of its establishment and business activities in the application form.
Nevertheless, applicants should still consider the residence provisions and other requirements contained in the specific DTA under which benefits will be claimed.
A CoR is not simply a general-purpose certificate showing that a business owns a Hong Kong company.
The application relates to claiming tax benefits under a DTA between Hong Kong and another jurisdiction.
Before applying, determine:
Which jurisdiction is involved?
What type of income is involved?
Which DTA benefit is being claimed?
For which calendar year is the certificate required?
These questions will also determine which application form should be used.
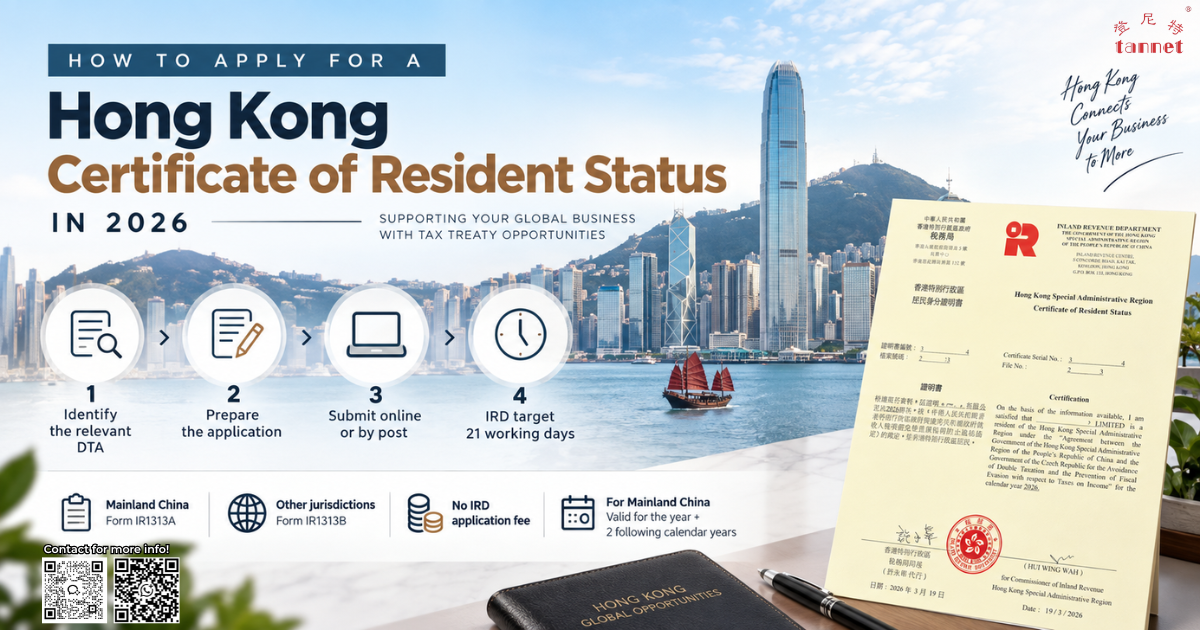
For companies, partnerships, trusts and other bodies of persons, the current forms are:
Mainland China — Form IR1313A
Other DTA jurisdictions — Form IR1313B
For individuals, the corresponding forms are IR1314A and IR1314B.
This distinction is particularly important for Hong Kong companies conducting business with Mainland China.
The exact information required depends on the applicant, treaty jurisdiction and circumstances of the claim.
For applications concerning jurisdictions other than Mainland China, for example, the IRD’s Business Tax Portal application asks for information concerning the relevant income, including its nature and amount and details of its beneficial owner.
The IRD may request supplementary information when reviewing an application.
Companies should therefore ensure that the information submitted is consistent with their actual corporate structure and cross-border transaction.
Applications can currently be submitted online, by post or in person.
Online applications can be submitted by the applicant or an appointed service agent, such as a company secretary or tax representative, through the relevant eTAX portal.
Paper applications can also be submitted to the IRD’s Tax Treaty Section in Hong Kong.
There is currently no IRD application fee for a CoR.
The IRD’s current target is to issue a Certificate of Resident Status or a notification from the assessing officer within 21 working days after receiving a properly completed application.
The notification may instead request additional information or inform the applicant that the application cannot be accepted.
Therefore, 21 working days should not be interpreted as a guaranteed approval period.
Hong Kong companies conducting business with Mainland China should pay particular attention to the special administrative arrangement.
A CoR issued for a particular calendar year under the Mainland–Hong Kong Arrangement generally serves as proof of Hong Kong resident status for that calendar year and the following two calendar years.
A new application for those subsequent two years is generally unnecessary, provided there has been no change in circumstances causing the applicant to cease meeting the conditions for the relevant tax benefits.
There has also been an important digitalisation change: for successful CoR applications relating to Mainland China, the IRD has issued digital Certificates of Resident Status instead of paper certificates since 10 November 2025.
No.
Being incorporated in Hong Kong generally places a company within the categories that can apply, but an application is still assessed in the context of the relevant DTA.
More importantly, receiving the certificate does not itself guarantee that the overseas jurisdiction will grant the requested treaty benefit.
Companies should therefore distinguish between:
being eligible to apply for a CoR
and
qualifying for a particular tax treaty benefit.
They are related, but they are not the same question.
For businesses already using a Hong Kong company for cross-border transactions, it may be worthwhile reviewing whether a Certificate of Resident Status is relevant before claiming treaty benefits overseas.
TANNET can assist businesses with Hong Kong corporate services and the preparation and handling of Certificate of Resident Status applications based on their specific cross-border circumstances.
Need assistance with a Hong Kong Certificate of Resident Status? Contact TANNET to discuss your case.
Official reference: Hong Kong Inland Revenue Department — Certificate of Resident Status
Official Service Hotline: +86-755-82148419
Cell: +86-13823131503;+60 19-309 2363
WeChat ID: 13823131503;
WhatsApp:+86-13823131503;+60 19-309 2363
Email: mytannet08@gmail.com; susiehu@citilinkia.com