Hiring employees in Hong Kong comes with statutory responsibilities, and one of the most important is Mandatory Provident Fund (MPF) registration. Whether you operate a newly incorporated Hong Kong company, manage an overseas business with local employees, or plan to expand your workforce, understanding Hong Kong MPF employer registration is essential for maintaining compliance.
Under Hong Kong’s Mandatory Provident Fund Schemes Ordinance, most employers are required to enrol eligible employees in an MPF scheme and make regular contributions. Failure to fulfil these obligations may result in financial penalties and legal consequences.
This guide explains the MPF registration requirements, application process, contribution rates and ongoing responsibilities for Hong Kong employers.
1. What Is MPF in Hong Kong?
The Mandatory Provident Fund (MPF) is Hong Kong’s compulsory retirement savings system. It requires employers and eligible employees to make regular contributions to an approved MPF scheme.
The system is designed to help employees accumulate retirement savings throughout their working lives.
For businesses, MPF compliance is part of the statutory employment obligations. Employers must select an MPF scheme, register eligible employees, calculate contributions and submit payments within the prescribed deadlines.
2. Who Needs to Register for MPF?
Generally, employers must enrol employees in an MPF scheme if they are:
- Aged 18 to 64.
- Employed under a continuous employment contract for 60 days or more.
- Not covered by an applicable statutory exemption.
The 60-day rule generally applies to full-time and part-time employees. Casual employees in the construction and catering industries are subject to specific arrangements and may need to be enrolled regardless of the employment period.
Certain individuals are exempt, including qualifying employees covered by other statutory retirement schemes or specific exemption categories.
Important: Employers should assess each employee’s eligibility individually rather than assuming that short-term, part-time or foreign-owned business arrangements automatically qualify for exemption.
3. Hong Kong MPF Contribution Rates
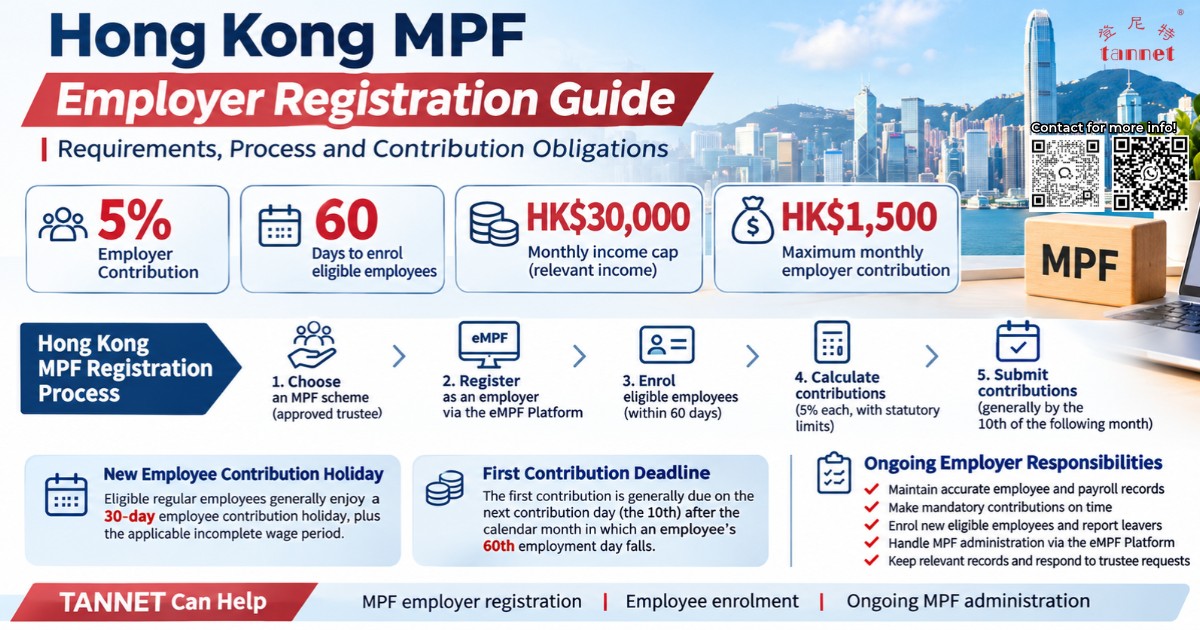
Both employers and employees are generally required to contribute 5% of the employee’s relevant income, subject to the statutory minimum and maximum relevant income levels.
The standard monthly contribution framework is:
- Minimum relevant income: HK$7,100.
- Maximum relevant income: HK$30,000.
- Employer contribution: 5%.
- Employee contribution: 5%, where applicable.
For example, an employee earning HK$20,000 per month would generally have:
- Employer contribution: HK$1,000.
- Employee contribution: HK$1,000.
- Total monthly MPF contribution: HK$2,000.
For employees earning below HK$7,100 monthly, employers must still make the 5% contribution, while employees are generally not required to contribute.
For employees earning above HK$30,000 monthly, mandatory contributions are capped at HK$1,500 each for the employer and employee.
These are standard mandatory contribution rules. Voluntary contributions may be made separately under the applicable scheme arrangements.
4. How to Register for an MPF Scheme as an Employer
Hong Kong MPF employer registration generally involves the following steps.
Step 1: Select an MPF Trustee and Scheme
Employers must select an MPF scheme operated by an approved MPF trustee. When comparing providers, consider administration services, investment options, service fees and digital account management facilities.
Step 2: Complete Employer Registration
Submit the required employer registration documents and application forms to the selected MPF trustee.
Typical information includes:
- Hong Kong company name and registration details.
- Business Registration Certificate.
- Employer’s contact information.
- Authorised signatory details.
- Relevant business and payroll information.
Additional documentation may be requested depending on the trustee.
Step 3: Register Eligible Employees
Employers must provide the required employee information and complete the relevant enrolment procedures within the statutory timeframe.
Employees should receive the necessary scheme information and documentation.
Step 4: Calculate and Arrange MPF Contributions
Employers must calculate contributions according to each employee’s relevant income and applicable contribution period.
Both employer and employee contributions must be handled correctly, including deductions from employee salaries where applicable.
Step 5: Submit Contributions on Time
Employers must arrange contributions by the applicable statutory deadlines. For most monthly-paid employees, contributions are payable on or before the 10th day of the following month.
Late or incorrect payments may result in surcharges and other enforcement consequences.
5. Ongoing MPF Responsibilities for Employers
MPF registration is not a one-time administrative exercise. Employers must maintain ongoing compliance throughout the employment relationship.
Key responsibilities include:
- Maintaining accurate employee and payroll records.
- Making mandatory contributions on time.
- Providing contribution statements and relevant information to employees.
- Reporting employee departures and changes in employment circumstances.
- Enrolling newly eligible employees.
- Handling final contributions when employees leave.
- Responding to MPF trustee requests and maintaining supporting records.
Employers should also be aware that Hong Kong abolished the MPF offsetting arrangement from 1 May 2025. Employers can no longer use mandatory employer MPF contributions to offset severance payments or long service payments attributable to an employee’s post-transition employment period.
This change should be considered when reviewing payroll and employee termination procedures.
6. What Happens If Employers Fail to Register or Contribute?
Failure to comply with MPF requirements can expose employers to statutory consequences.
Depending on the nature of the breach, employers may face:
- Financial penalties for failing to enrol eligible employees.
- Surcharges for late contribution payments.
- Recovery action for outstanding contributions.
- Criminal prosecution for serious or repeated non-compliance.
Employers should therefore establish proper MPF administration procedures from the beginning of their operations.
7. Professional Assistance for Hong Kong MPF Registration
For overseas business owners and newly established Hong Kong companies, navigating MPF registration and ongoing administration can be challenging, particularly when managing employees, payroll and statutory deadlines from another jurisdiction.
TANNET provides Hong Kong MPF-related corporate support, including employer registration, employee enrolment coordination and ongoing MPF administration.
Whether you are establishing a new Hong Kong company or expanding your existing workforce, having the appropriate administrative support can help streamline registration and maintain compliance with local requirements.
Planning to hire employees in Hong Kong? Contact TANNET to understand your MPF registration requirements and arrange the necessary employer and employee enrolment procedures.
📞 Free 1-on-1 Consultation Now,
Official Service Hotline: +86-755-82148419
Cell: +86-13823131503;+60 19-309 2363
WeChat ID: 13823131503;
WhatsApp:+86-13823131503;+60 19-309 2363
Email: mytannet08@gmail.com; susiehu@citilinkia.com