Key Takeaway
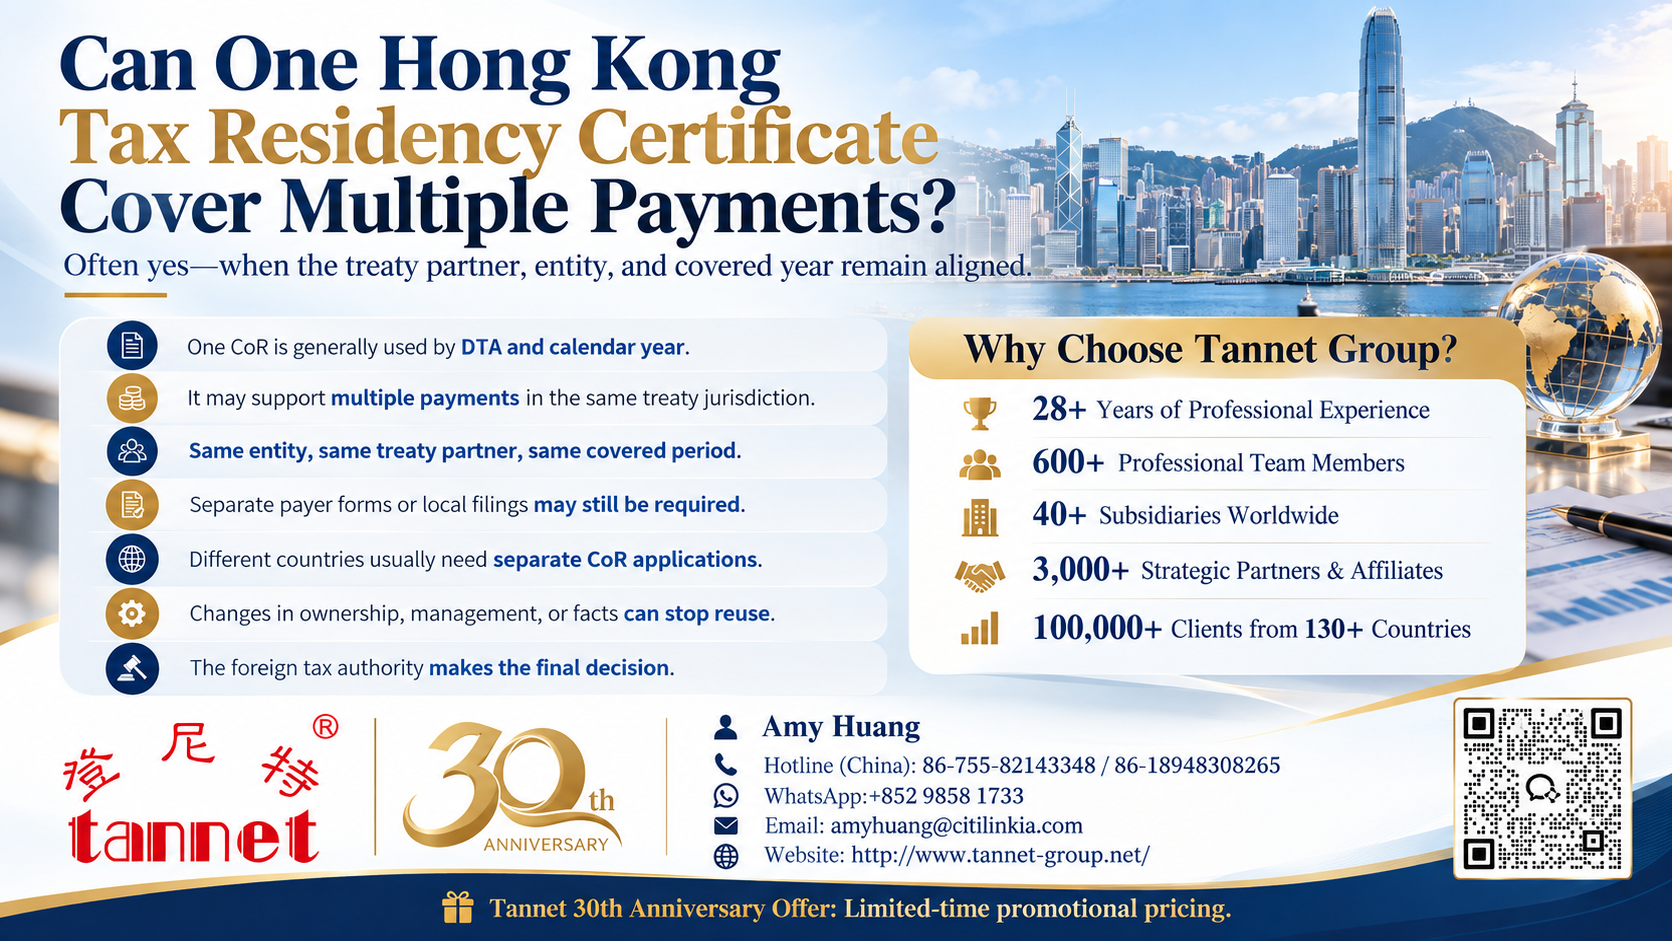
One Hong Kong Certificate of Resident Status may support multiple payments when the same company, treaty partner, and covered calendar year remain relevant.
The certificate proves Hong Kong resident status. It does not approve each payment or guarantee a reduced foreign tax rate. This matters to holding, finance, licensing, and operating companies receiving recurring dividends, interest, royalties, or service income.
The main caution is source-country procedure. Each payer, payment, or income type may still require a separate relief form, beneficial ownership analysis, or refund claim. Different treaty partners normally require separate Hong Kong CoRs.
The short answer is conditional
The Hong Kong Inland Revenue Department states that generally only one Certificate of Resident Status is issued for each DTA for each year.
That wording indicates that the certificate is organised by applicant, treaty relationship, and calendar year. It is not normally issued once for every invoice, dividend, interest instalment, or royalty payment.
Therefore, one CoR can often be presented as residence evidence for several payments involving the same treaty partner and covered period.
However, the CoR does not itself combine the foreign tax claims. The payer or foreign tax authority may require a separate filing for each payer, payment, contract, tax office, or income category.
Understand what the certificate proves
A CoR proves that the applicant is treated as a Hong Kong resident for the relevant DTA purpose.
It does not certify the payment amount. It does not determine whether the payment is a dividend, interest, royalty, service fee, or business profit.
It also does not certify beneficial ownership, an ownership threshold, a holding period, permanent establishment status, or satisfaction of an anti-abuse rule.
The IRD expressly states that the treaty partner ultimately decides whether relief from foreign tax can be granted.
When one certificate may support several payments
Reuse is more likely to be appropriate when all core facts remain aligned.
- The recipient is the same Hong Kong legal entity.
- The payer or payers are located in the same DTA jurisdiction.
- The payments fall within the calendar year or years stated on the certificate.
- The company’s residence and material circumstances have not changed.
- The local authority accepts the certificate for repeated relief claims.
- The certificate is supported by accurate payment-level records.
Meeting these points does not remove other treaty tests. It only makes reuse of the residence evidence more coherent.
Multiple payments from one payer
Recurring payments under one contract are the simplest scenario.
Examples include monthly interest under a loan, quarterly royalties under a licence, or several service invoices under one agreement.
One CoR may be accepted throughout the covered period. The payer may retain it in its tax file and apply the treaty procedure to later payments.
Still, confirm whether the payer needs a new declaration, beneficial ownership confirmation, or local relief form for each payment.
Multiple payers in the same jurisdiction
A CoR may remain valid evidence of residence even when several unrelated payers are in the same treaty jurisdiction.
The certificate belongs to the Hong Kong applicant. It is not issued to one payer.
Yet each payer may have its own withholding obligations and documentation standards. One payer may accept a copy. Another may request an original or an electronically verifiable version.
Each payer should receive only the information needed for its transaction. Maintain a distribution log to show which certificate supported which claim.
Multiple income types
One CoR may support residence evidence for dividends, interest, and royalties received from the same treaty partner during the covered year.
The application forms ask for the nature and amount of income for each year of claim. Known income streams should therefore be described accurately when applying.
Each income type is governed by a different treaty article and may have a different maximum withholding rate.
Beneficial ownership is especially important for dividends, interest, and royalties. A company required to pass the payment to another person may not qualify as beneficial owner.
Different treaty partners require separate treatment
A CoR issued in respect of one DTA should not be treated as a universal residence certificate for every country.
The IRD says generally only one CoR is issued for each DTA for each year. The relevant DTA must already be effective.
If a Hong Kong company receives payments from two treaty jurisdictions, it should normally apply in relation to each DTA.
The foreign procedures may differ. One jurisdiction may use relief at source. Another may require full withholding followed by a refund.
Different calendar years
The IRD FAQ says one CoR application may cover at most three calendar years of claim.
That does not mean every certificate automatically covers three years. Check the years stated on the issued certificate and the foreign authority’s requirements.
For the Chinese Mainland, a special administrative arrangement generally allows a certificate issued for one calendar year to prove Hong Kong residence for that year and the two succeeding calendar years.
This special treatment depends on unchanged circumstances. It should not be assumed for other treaty partners.
Changes that can prevent reuse
Do not reuse a certificate without review when material facts have changed.
Relevant changes include a new legal recipient, company name change, merger, re-domiciliation, altered ownership, changed management and control, new headquarters, or a different beneficial owner.
A major change in business activity or payment flow can also affect the treaty analysis.
The IRD online service allows supplementary information to be submitted for an application. Use it when information needs correction or updating during processing.
A practical decision process
- Read the treaty partner and calendar year on the certificate.
- Match the legal recipient to the applicant named on the certificate.
- Classify each payment under the correct treaty article.
- Test beneficial ownership and other substantive conditions for each income stream.
- Confirm the foreign filing requirement with the payer or local adviser.
- Record whether an original, copy, or digital certificate is accepted.
- File separate local claims where required.
- Stop reuse when facts or the covered period change.
Common mistakes
- Treating a CoR as a worldwide certificate.
- Using one group company’s certificate for another entity.
- Ignoring the calendar year shown on the certificate.
- Assuming one certificate replaces every foreign relief form.
- Applying one treaty rate to different income categories.
- Reusing a certificate after ownership or management changes.
- Forgetting payment-level withholding records and tax vouchers.
Frequently asked questions
Q1. Can one CoR cover several invoices from the same customer?
Potentially, yes, if the same applicant, treaty partner, and covered period apply. The payer may still require a declaration or filing for each invoice.
Q2. Can it cover payments from several customers in one country?
It may serve as the same residence evidence, but each payer must follow local withholding procedures and may request its own copy or form.
Q3. Can the same certificate cover dividends and interest?
It may prove residence for both. The treaty conditions, rates, beneficial ownership, and supporting documents must be tested separately.
Q4. Can it be used in two countries?
Generally, no. A CoR is issued in respect of a particular DTA. Separate treaty partners require separate analysis and normally separate applications.
Q5. Does one application cover several years?
Generally, three calendar years for Chinese Mainland claims, and one calendar year for other jurisdictions — subject to the relevant tax authority’s requirements. Use only the years actually stated or otherwise officially accepted.
Q6. Is the Chinese Mainland rule different?
Yes. A certificate for one calendar year generally proves residence for that year and the next two years if circumstances remain unchanged.
Q7. Does the CoR guarantee relief for every payment?
No. The treaty partner decides each relief claim under its law, the DTA, and its procedures.
Additional control checks
Create a payment register showing each payer, contract, income type, gross amount, withholding date, treaty article, local form, and submission deadline.
Check all relevant facts documents evidence timelines procedures records and applicable treaty deadlines carefully.
When Tannet may assist
Tannet may assist with mapping payments to treaty partners and years, selecting the correct application, organising payment-level evidence, checking reuse risks, maintaining a certificate register, and coordinating with foreign advisers. Final acceptance depends on the treaty partner and the facts of each claim.
Written by: Tannet Business Services Team
Reviewed by: Consultant Amy Huang
First published: 21 Oct. 2026
Last reviewed: 21 Oct. 2026
30th Anniversary Offer: To celebrate Tannet’s 30th anniversary, we are offering exclusive limited-time promotional pricing. Slots are limited and available on a first-come, first-served basis. Contact Consultant Amy Huang for details.
————————————————Simplifying Business, Empowering Entrepreneurs————————————————