For individuals and companies conducting cross-border activities, the Hong Kong Certificate of Resident Status (CoR) can be an important document when claiming benefits under a tax treaty.
But who can apply? What information is required? And how long does the process take?
Here is a practical overview for 2026.
What Is a Certificate of Resident Status?
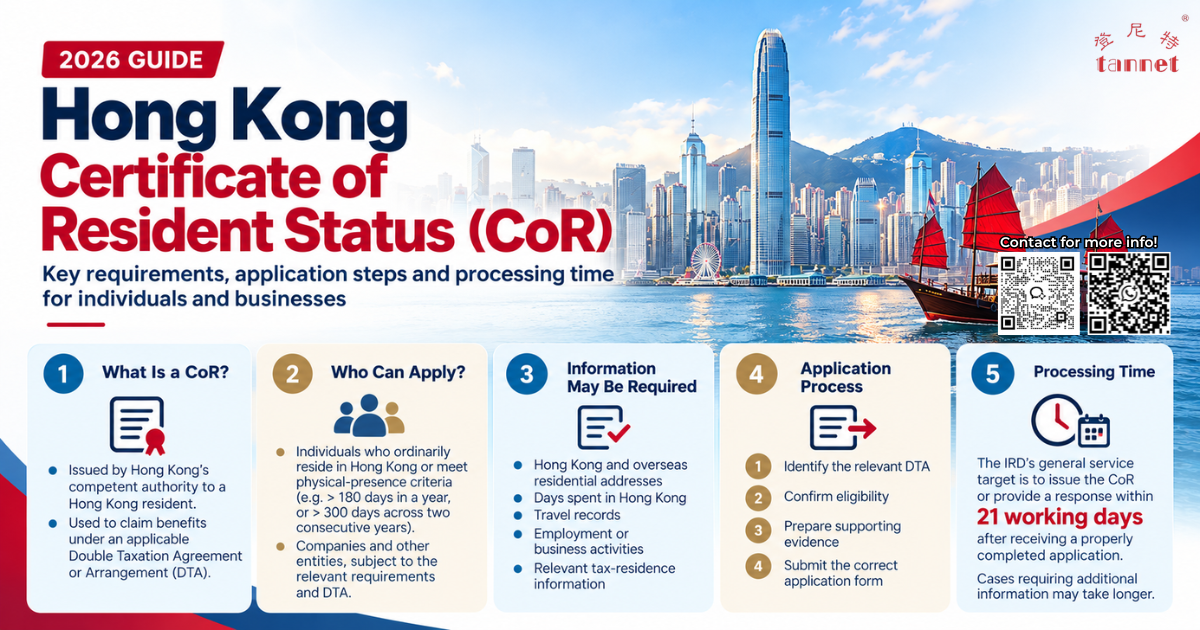
A CoR is issued by Hong Kong’s competent authority to a Hong Kong resident who requires proof of resident status to claim benefits under an applicable Comprehensive Double Taxation Agreement or Arrangement (DTA).
It is therefore not a general certificate obtained simply because someone holds a Hong Kong visa or operates a Hong Kong company.
There should be a relevant treaty purpose.
Who Can Apply?
For individuals, the Inland Revenue Department generally considers applicants who ordinarily reside in Hong Kong or meet applicable physical-presence criteria.
These include staying in Hong Kong for:
- more than 180 days during a year of assessment; or
- more than 300 days across two consecutive years of assessment, one being the relevant year.
Companies and other entities can also apply subject to the applicable requirements and DTA.
The precise residence definition under the relevant treaty should always be checked.
Which Application Form Is Required?
The application route depends on the treaty jurisdiction and applicant type.
For individuals seeking benefits under the Mainland-Hong Kong arrangement, the IRD provides the relevant Mainland-specific application form.
Different forms apply to companies and to applications concerning other treaty jurisdictions.
Applicants should therefore identify the relevant DTA before preparing the application rather than submitting a generic request for “Hong Kong tax residency.”
What Information May Be Required?
For individuals, information may include:
Hong Kong residential address
overseas residential address
days spent in Hong Kong
travel records
Hong Kong employment
Hong Kong business activities
relevant tax-residence information
For corporate applicants, information may concern incorporation, business activities, management and control, depending on the applicant and relevant treaty.
Additional supporting information may be requested where the IRD considers it necessary.
Step 1: Identify the Relevant DTA
Before applying, determine which jurisdiction is involved.
Hong Kong has established DTAs with numerous jurisdictions.
The applicant should identify the particular treaty and the benefit being claimed.
This prevents the CoR application from being treated as an isolated administrative exercise.
Step 2: Confirm Eligibility
The applicant should then determine whether the relevant Hong Kong residence requirements are satisfied.
For internationally mobile individuals, this may involve reviewing physical presence and actual residence circumstances.
For companies, corporate residence requirements should be considered separately.
Step 3: Prepare Supporting Information
Applicants should ensure that the information submitted is consistent and supported by appropriate records.
For individuals, maintaining travel and residence records can be particularly important.
Where business activities are relevant, supporting information should accurately reflect what is genuinely conducted in Hong Kong.
Step 4: Submit the Application
Applications may be submitted using the applicable IRD procedure, including relevant electronic services where available.
Using the correct form and providing complete information can reduce unnecessary requests for clarification.
How Long Does the Application Take?
The IRD states that its service target is generally to issue the CoR—or notify the applicant of its decision, request further information or explain why the application cannot be accepted—within 21 working days after receiving a properly completed application.
Cases requiring additional information can take longer.
Applicants should therefore avoid leaving CoR applications until immediately before an overseas tax deadline.
Does Approval Guarantee DTA Benefits?
No.
Even after the IRD issues a CoR, the overseas treaty partner determines whether the applicant satisfies all conditions for the requested DTA benefit.
A CoR proves resident status for the relevant purpose; it does not independently create a tax exemption.
Prepare Before You Apply
The most effective approach is:
Identify the treaty → identify the tax benefit → confirm residence eligibility → prepare evidence → submit the correct application.
This is especially important for entrepreneurs and investors with income across multiple jurisdictions.
TANNET can assist individuals and businesses with Hong Kong Certificate of Resident Status applications, company incorporation, accounting and tax compliance, immigration and other cross-border corporate services. Early preparation can help make the CoR application process more efficient and reduce avoidable delays.
📞 Free 1-on-1 Consultation Now,
Official Service Hotline: +86-755-82148419
Cell: +86-13823131503;+60 19-309 2363
WeChat ID: 13823131503;
WhatsApp:+86-13823131503;+60 19-309 2363
Email: mytannet08@gmail.com; susiehu@citilinkia.com